The Triple-Swap Strategy, Finally Backtested With Real Swaps: the Carry Is Real, the Trade Is Not
Many brokers and forums say you can collect three nights of USDJPY swap every Wednesday while holding the trade for only a few hours. We tested it with real swaps. The swap was paid every week. The strategy still lost money.
Does the Wednesday triple-swap trade on USD/JPY work?
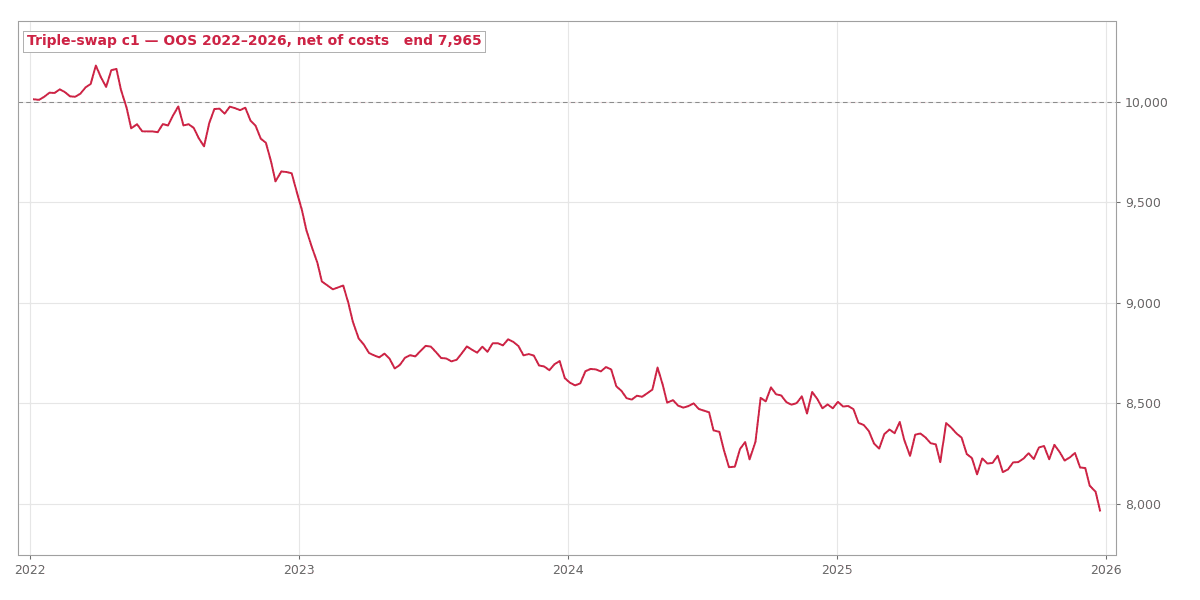
You get the swap, but the trade loses. The triple swap was paid every week, also in the out-of-sample test. But the strategy lost 20 to 36%. Its early profits came from a price move in the early Tokyo hours, and that move turned the other way after 2022.
What is the triple swap?
When you hold a forex trade past midnight, the broker pays or charges you a small fee. This is called swap (or rollover). On Wednesday, the broker charges three nights of swap at once, to cover the weekend.
A buy trade on USDJPY earns positive swap. So many broker education pages and forum posts suggest this plan:
- Buy USDJPY on Wednesday evening.
- Hold it past midnight.
- Close it about one hour later.
- Collect three nights of swap for only a few hours of risk.
As far as we know, nobody has ever published a real backtest of this strategy. The reason is simple: most backtests do not include swap at all.
Ours does. Our tester uses the real swap settings for each symbol. Before we wrote any code, we checked it: a buy on USDJPY earns +10.064 points per night, and three times that on Wednesday. That is about 3 pips of swap per weekly trade, for free. At least, that is the claim.
The swap was paid, exactly as promised
This part of the claim is true. We can show it trade by trade.
In our first quick test, every trade held over Wednesday midnight collected about $9.90 of swap on a 0.34-lot position. That is exactly three nights at the stated rate, to the cent.
Over the full in-sample period (2019 to 2022), each of the final candidates collected over a thousand dollars of swap alone. In-sample means the data we use to build and tune the strategy.
The in-sample results looked too good
In-sample, one group of settings looked excellent. Every setting that entered at 23:00 UTC made money: 12 of 12. Profit factors (gross profit divided by gross loss) went up to 1.85 on real tick data.
When every setting in a group wins, it is tempting to trust it. But our checking tools are built to doubt exactly this kind of result. Before we picked any settings, they showed warning signs:
- Good results only appeared at one exact point. Nearby settings did not give similar results.
- Results dropped sharply right at the 22:00 entry time.
- The settings around the best ones were weak.
We still picked the top three candidates. Then we ran them once on the out-of-sample data (new data the strategy was not built on). That one test is exactly what this data is for.
The out-of-sample test failed badly
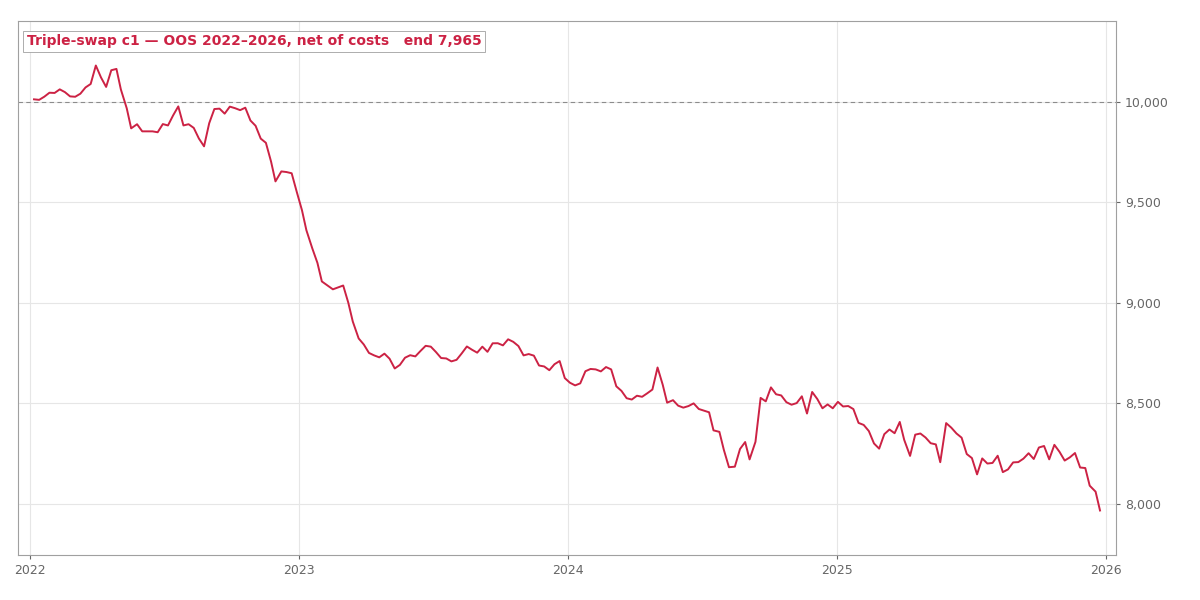 Out-of-sample equity of the top candidate, 2022 to 2026, net of costs. The swap kept arriving every Wednesday while the account lost a fifth of its value.
All three candidates failed:
- Profit factors from 0.58 to 0.68.
- Drawdowns (the biggest fall from a high point) up to 38.5%.
- Each one failed eight of our quality checks.
Here is the important part, and the reason we publish this result. The swap stayed positive the whole time. Over 208 out-of-sample Wednesdays, the candidates collected $1,305 to $2,010 of swap, exactly as expected. But the price moves lost three to five times that amount.
So the in-sample profits never came from the swap. They came from a price move between 23:00 and the early Tokyo hours. This move existed from 2019 to 2021. In 2022, Japan started to step into the market to support the yen. The price move then turned the other way.
The swap was real in both periods. But it was too small to matter. Three pips a week cannot pay for hours of USDJPY risk, in a market where the pair can move a hundred pips overnight.
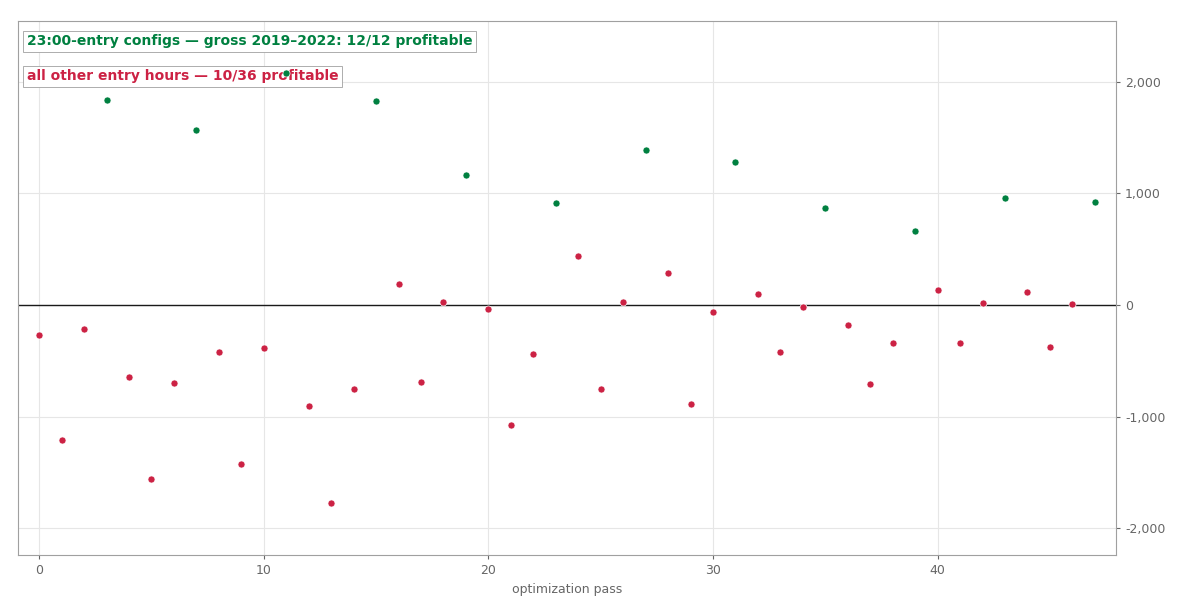 The in-sample results that fooled the test: every 23:00-entry configuration profitable, everything else flat or negative.
What we learned
1. A swap strategy with market risk is really a bet on the price. You can check the swap easily. But the price risk is what you actually hold. We now use this rule for every swap idea.
2. The timing of the swap is different in real life. Real brokers charge swap at 5pm New York time, not at midnight UTC. So a live trader holds the trade during a different market session than a backtest that uses a UTC clock. Our strategy failed before this mattered. But even a good backtest result would have needed a second test before trading it live.
3. Our tools helped us twice. Because our tester includes real swap, we could test the swap claim at all. And our check for stable settings found the weakness before the out-of-sample test proved it. When the warning from your checks and a beautiful in-sample table disagree, believe the warning.
Anyone trading the triple swap live since 2022 has collected their three pips every Wednesday. At the same time, their account was slowly losing money. This is a very hard kind of losing strategy to spot, because the part you can see really is working.
Case 006 in one PDF: the exact rules, how we tested them, and what we found. Your email unlocks it and the other 11 case files, plus every new one as it lands.
Run the numbers yourself
The free calculators behind the sizing and robustness checks in this test. No signup.